
With the recent lower interest rates, many homeowners are wondering if they should refinance.
To decide if refinancing is the best option for your family, start by asking yourself these questions:
Why do you want to refinance?
There are many reasons to refinance, but here are three of the most common ones:
- Lower your interest rate and payment – This is the most popular reason. If you have a 5% interest rate or higher, it might be worth seeing if you can take advantage of the current lower interest rates, hovering below 4%, to reduce your monthly payment and overall cost of the loan.
- Shorten the term of your loan – If you have a 30-year loan, it may be advantageous to change it to a 15 or 20-year loan to pay off your mortgage sooner.
- Cash-out refinance – With home prices increasing, you might have enough equity to cash out and invest in something else, like your children’s education, a vacation home, or a new business.
Once you know why you might want to refinance, ask yourself the next question:
How much is it going to cost?
There are fees and closing costs involved in refinancing, and Lenders Network explains:
“If you were to refinance that loan into a new loan, total closing costs will run between 2%-4% of the loan amount.”
They also explain that there are options for no-cost refinance loans, but be on the lookout:
“A no-cost refinance loan is when the lender pays the closing costs for the borrower. However, you should be aware that the lender makes up this money from other aspects of the mortgage. Usually pay charging a slightly higher interest rate so they can make the money back.”
If you’re comfortable with the costs of refinancing, then ask yourself one more question:
Is it worth it?
To answer this one, we’ll use an example. Let’s assume you have a $200,000 home loan. A 4% refinance cost will be $10,000. If you want to lower your interest rate from 6% to 4%, then refinancing is going to save you $244 per month. To break even ($10,000/$244), you need to continue owning your home for over 40 months.
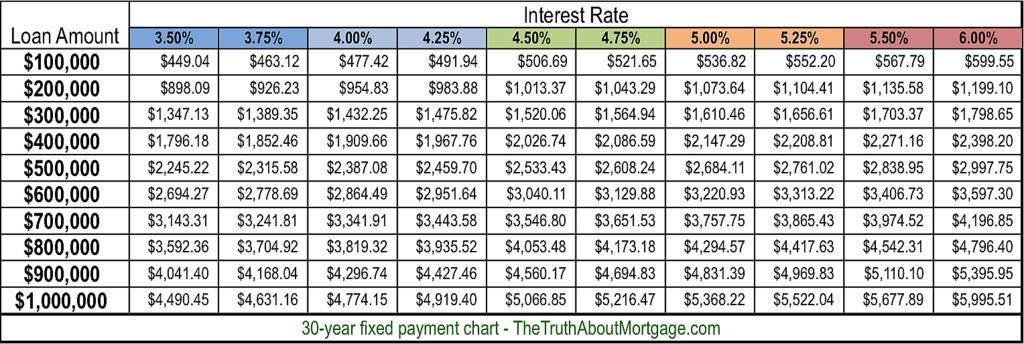
Now that you know how the math shakes out, think about how much longer you’d like to own your current home. If you plan to stay for more than 3 years, then maybe it is advantageous for you to refinance.
If, however, your current home does not fulfill your present needs, you might want to consider using your potential refinance costs for a down payment on a new move-up home. You will still get a lower interest rate than the one you have on your current house, and with the equity you’ve already built, you can finally purchase the home of your dreams.
Bottom Line
There are many opportunities for growth in the current real estate market. To find out what’s right for your family, let’s get together to help you understand your options and guide you toward the best decision.
source https://www.simplifyingthemarket.com/en/2019/07/16/should-i-refinance-my-home/?a=489394-750b3ad95b7715aa39b3f5a8d59f5d51
Comments
Post a Comment